
Concessional Credit Matching for Marginalized Entrepreneurs
Connecting Scheduled Caste entrepreneurs with tailored NSFDC concessional schemes covering up to 90% of project costs at 4.0% to 8.0% interest rates through solvent, low-NPA Channel Partners.
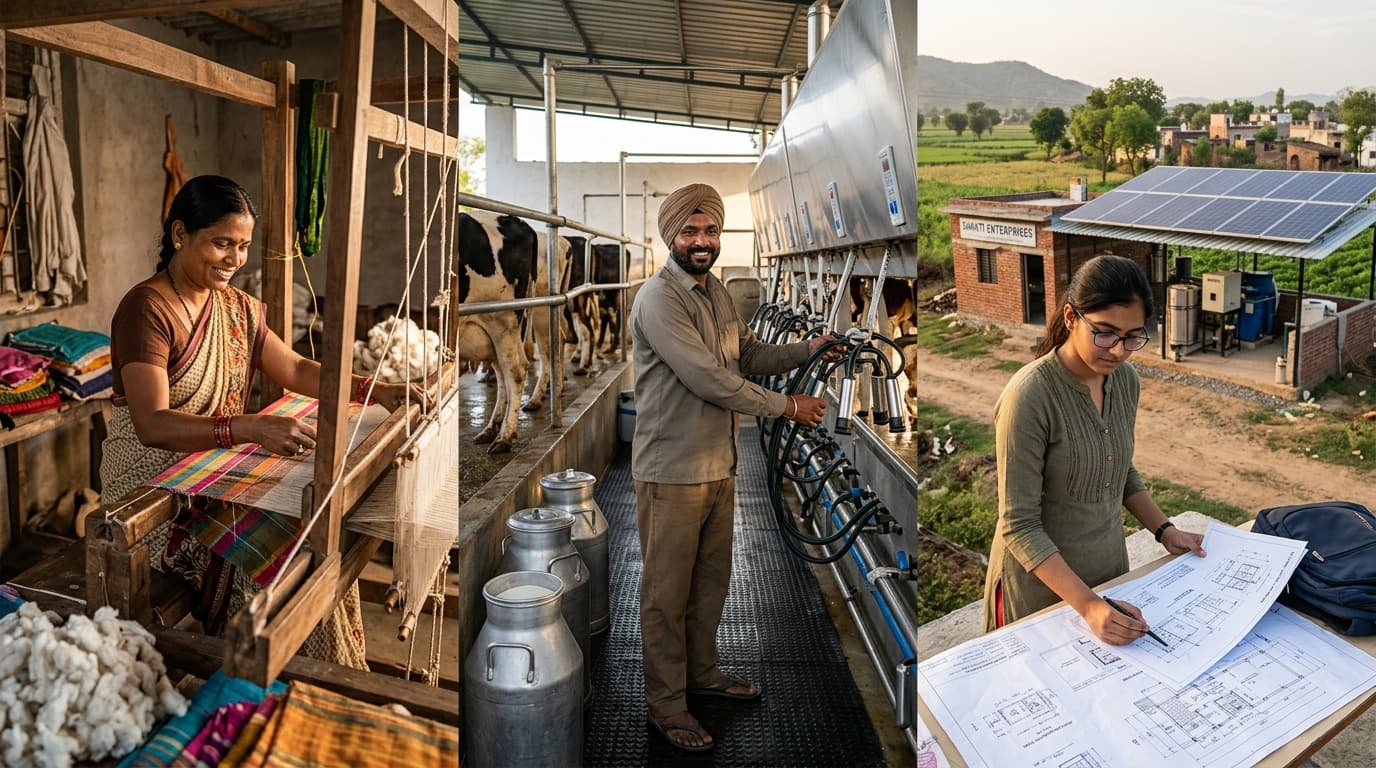
Empowering SC Artisans, Dairy Farmers & Micro-Enterprises
Smart Scheme Recommender
Deliverable 1: Evaluates project type, cost, income, and category to instantly match the statutory MoSJE credit scheme.
Micro Credit Finance Scheme (MCF)
Tailored concessional assistance covering up to 90% of your project cost under NSFDC guidelines.
Matched for your Retail & Grocery Kiosk profile, cost, income, and category.
Statutory MoSJE & NSFDC Concessional Schemes
Targeted affirmative credit windows covering up to 90% of project costs at 4.0% to 8.0% interest rates.
How the Channel Finance System Works
MoSJE (Ministry of Social Justice and Empowerment) and NSFDC (National Scheduled Castes Finance and Development Corporation) do not disburse direct loans to citizens. Concessional credit is strictly routed through authorized Channel Partners. SchemeSetu eliminates misrouted applications by routing only to solvent branches.
State Channelizing Agencies
State-level government corporations designated for Scheduled Caste development, disbursing direct micro-credit and affirmative women schemes.
Public Sector Banks
Nationalized commercial banks (SBI, PNB, Canara Bank) processing medium-to-large Term Loans (up to ₹50 Lakhs) and enterprise credit.
Regional Rural Banks
Grassroots rural banking institutions servicing agricultural, dairy, and rural transport enterprise loans in semi-urban and rural areas.
Microfinance Institutions
Non-Banking Financial Companies accredited for rapid micro-credit (MCF up to ₹1.40L) directly to self-help groups and small vendors.
When beneficiaries apply to banks with non-performing asset (NPA) rates above 10% or exhausted statutory quotas, applications get stalled or rejected. SchemeSetu calculates a live Solvency Score, automatically routing you only to financially sound institutions with active disbursement quotas.
Secure & Verified Process
All applications are pre-screened under official MoSJE/NSFDC affirmative guidelines.